
Oilfield services company Halliburton (NYSE:HAL) beat Wall Street’s revenue expectations in Q3 2026, with sales up 1.8% year on year to $5.70 billion. Its non-GAAP profit of $0.60 per share was 2.6% above analysts’ consensus estimates.
Is now the time to buy Halliburton? Find out by accessing our full research report, it’s free.
Halliburton (HAL) Q3 2026 Highlights:
- Revenue: $5.70 billion vs analyst estimates of $5.59 billion (1.8% year-on-year growth, 2.1% beat)
- Adjusted EPS: $0.60 vs analyst estimates of $0.58 (2.6% beat)
- Adjusted EBITDA: $1 billion vs analyst estimates of $1.02 billion (17.5% margin, 2.4% miss)
- Operating Margin: 10.9%, up from 6.4% in the same quarter last year
- Free Cash Flow Margin: 2.7%, down from 4.1% in the same quarter last year
- Market Capitalization: $27.48 billion
Company Overview
Behind nearly every oil and gas well drilled worldwide, Halliburton (NYSE:HAL) provides drilling, completion, and production services that help oil and gas companies extract hydrocarbons from underground reservoirs.
Revenue Growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Regrettably, Halliburton’s sales grew at a mediocre 9.5% compounded annual growth rate over the last five years. This was below our standard for the energy upstream and integrated energy sector and is a rough starting point for our analysis.
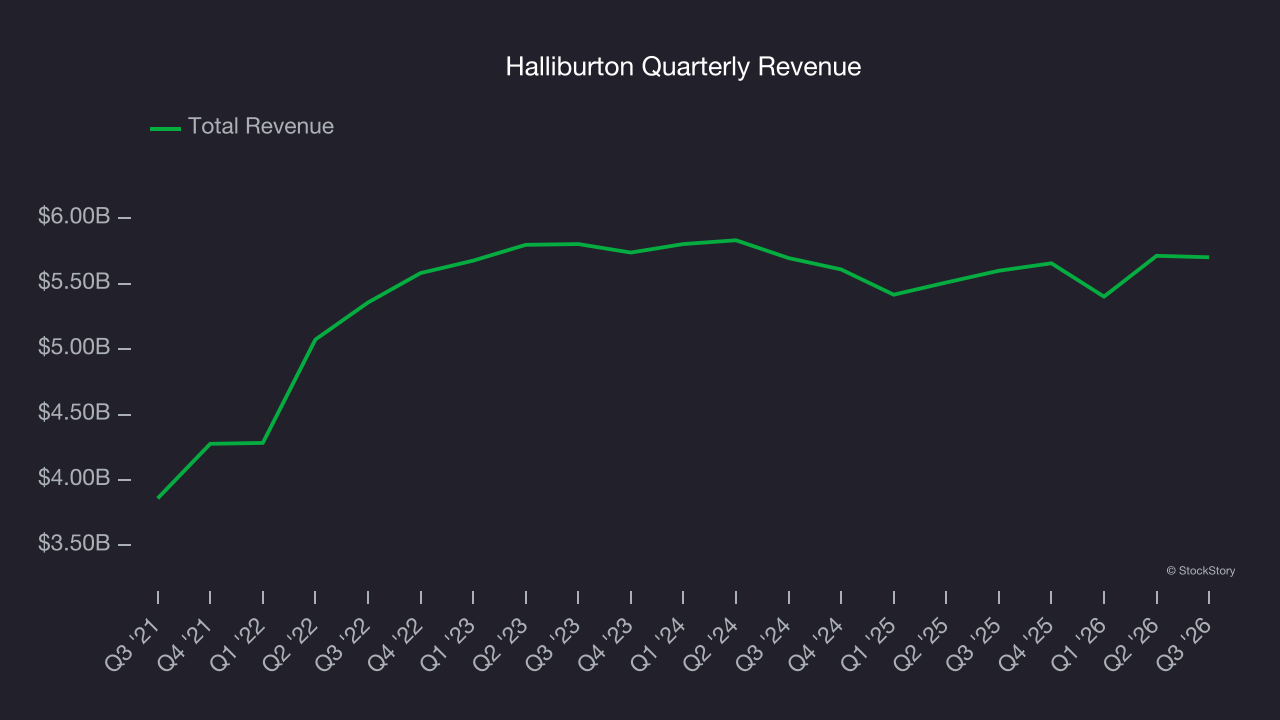
Even a long stretch in Energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies are built to grow regardless of the pricing regime. Halliburton’s annualized revenue growth of 2.9% over the last ten years is below its five-year trend, but we still think the results were good.
This quarter, Halliburton reported modest year-on-year revenue growth of 1.8% but beat Wall Street’s estimates by 2.1%.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted EBITDA Margin
Halliburton was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 20.1% was weak for an upstream and integrated energy business.
Analyzing the trend in its profitability, Halliburton’s EBITDA margin might have fluctuated slightly but has generally stayed the same over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
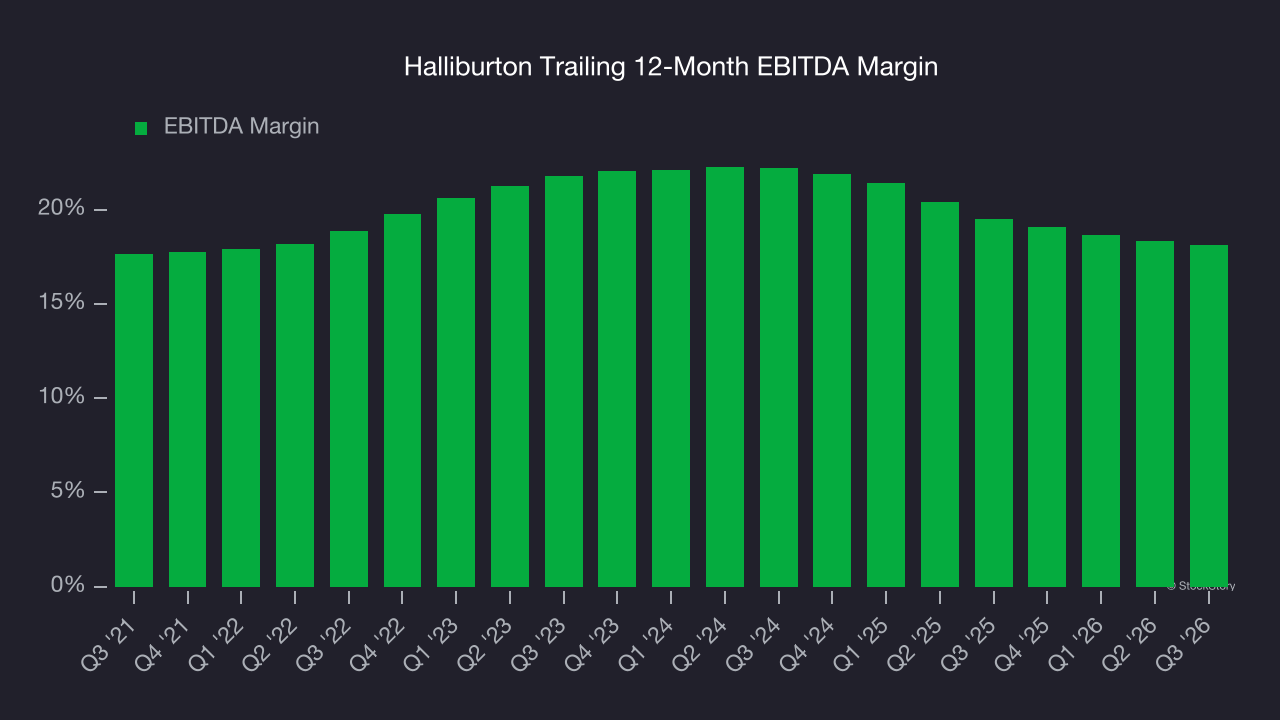
This quarter, Halliburton generated an EBITDA margin profit margin of 17.5%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable. This adjusted EBITDA fell short of Wall Street’s estimates.
Cash Is King
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two huge aspects of an Energy producer, so in order to understand a comprehensive picture of business quality, an investor needs to account for these. Said differently, adjusted EBITDA margins could be solid but free cash flow is abysmal because decline rates of the asset are extreme and the drilling is expensive. Free cash flow tells you about not only the economics of the production that has happened but how much it costs to stay in business as well (further drilling or extraction).
Halliburton has shown decent cash profitability, giving it some flexibility to reinvest or return capital to investors. The company’s free cash flow margin averaged 7.8% over the last five years, slightly better than the broader energy upstream and integrated energy sector.
Absolute FCF margin levels matter but so does stability of free cash flow. All else equal, we’d prefer a 25.0% average free cash flow margin that is quite steady no matter how commodity prices behave rather than extremely high margins when times are good and negative ones when they’re tough.
Halliburton’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 5.8 (lower is better), indicating excellent insulation from commodity swings. This stability supports capital access in downturns and positions Halliburton to act as a consolidator when weaker peers are forced to retrench.
You may be asking why we wait until the free cash flow line to perform this stability analysis versus commodity prices. Why not compare revenue or EBITDA to WTI Crude prices in the case of Halliburton? Because what ultimately matters is not how much revenue or profit you earn when prices are high but how much cash you can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging prowess to growth and maintenance capex to management behavior during good times and bad.
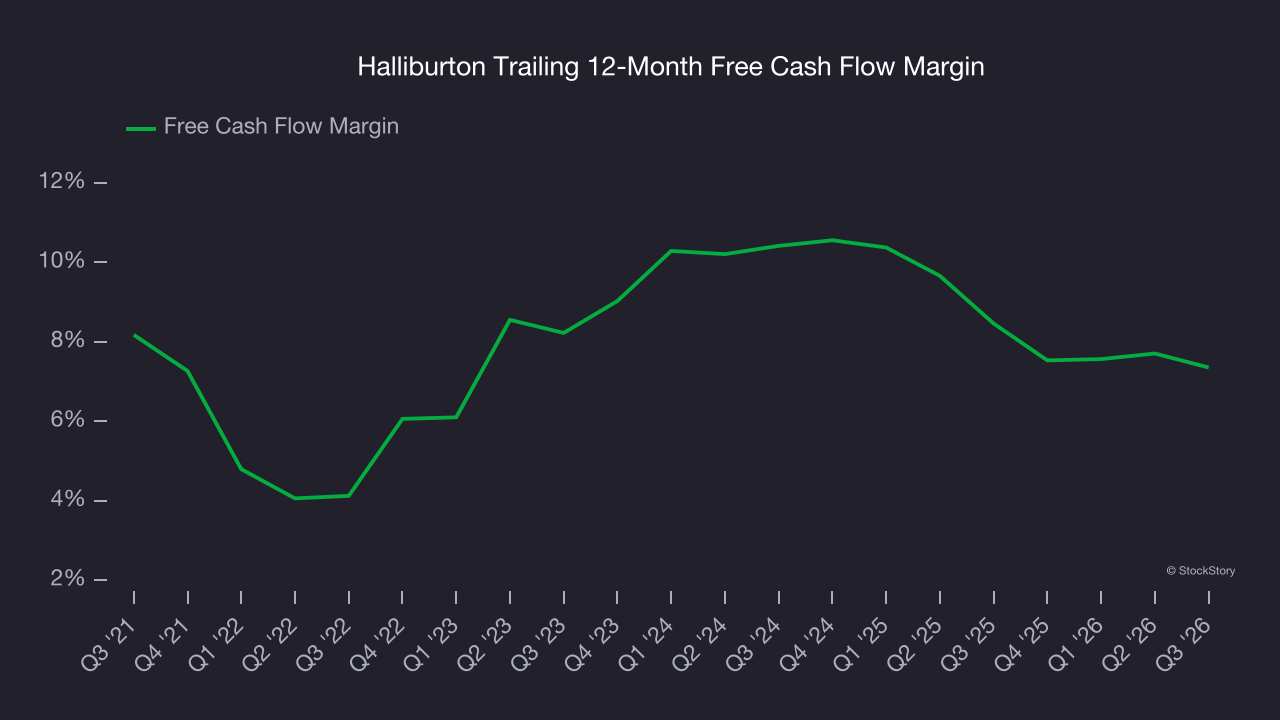
Halliburton’s free cash flow clocked in at $156 million in Q3, equivalent to a 2.7% margin. The company’s cash profitability regressed as it was 1.3 percentage points lower than in the same quarter last year, prompting us to pay closer attention. Short-term fluctuations typically aren’t a big deal because investment needs can be seasonal, but we’ll be watching to see if the trend extrapolates into future quarters.
Key Takeaways from Halliburton’s Q3 Results
We enjoyed seeing Halliburton beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its EBITDA missed. Zooming out, we think this was a mixed quarter. The stock traded up 4.1% to $34.34 immediately following the results.
So should you invest in Halliburton right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).